A portfolio manager at a national office and logistics REIT walked into her Q1 2026 board meeting with three reporting deadlines in one quarter: NABERS renewals across 47 assets, the GRESB submission window, and the fund’s first mandatory AASB S1 and S2 report. The board asked a fair question. Why are we reporting on the same buildings three different ways?
This is now the standard picture for Australian real estate in 2026. ASRS is mandatory for Group 1 entities, and Group 2 follows from 1 July 2026 per the Australian Accounting Standards Board. Getting NABERS, GRESB and ASRS to work together is what separates a lean reporting function from a team that spends half its year on duplicate work.
The Three-Framework Reality Inside Australian Portfolios
Each framework was built for a different audience, and each asks for different data:
- NABERS: A government rating scheme covering energy, water, waste and indoor environment. It applies to offices, shopping centres, hotels, data centres and apartments. Offices above 1,000 sqm need a NABERS Energy rating when they are sold or leased, under Commercial Building Disclosure rules published on the NABERS portal.
- GRESB: A voluntary benchmark that scores your portfolio on management, performance and development. Institutional investors increasingly flag missing GRESB scores during due diligence.
- ASRS (AASB S1 and S2): Mandatory climate reporting aligned with the global IFRS S1 and S2 standard. Group 1 started in 2025, Group 2 begins 1 July 2026, and Group 3 follows on 1 July 2027.
Knowing where these three overlap is what turns three reports into one dataset.
Where the Frameworks Actually Overlap
Four practical areas do most of the work:
- Scope 1 and 2 emissions: The energy data behind your NABERS ratings can also feed GRESB performance scores and ASRS emissions numbers. Same data, three uses.
- Governance: GRESB’s management score covers a lot of the same ground as ASRS governance disclosures. Board oversight, management responsibility, climate skills on the board, and incentive links all appear in both.
- Climate risk: The GRESB Resilience Module lines up closely with what ASRS S2 asks for on physical and transition risk, including scenario analysis.
- Water and waste: NABERS covers these well and feeds GRESB. ASRS only asks for them when the financial impact is material.
The point is architectural. Build one clean asset-level dataset, and it can feed all three.
Portfolio-Level Data as the Single Source of Truth
Most reporting inefficiency traces back to messy data. Property teams pull utility bills for NABERS. Asset managers build GRESB responses in spreadsheets. Finance builds a separate emissions ledger for ASRS. The result is three versions of the same buildings, each fine on its own and inconsistent when you put them side by side.
Bringing this into one data layer changes the economics. In practice that means:
- Automated feeds from utility bills, sub-meters and building management systems at asset level
- The same emissions factors used across every report and every year
- Tenant data-sharing agreements that fill in Scope 3 category 13, which covers emissions from tenant-occupied spaces
- Version-controlled calculations that can stand up to the auditor once ASRS assurance kicks in from year two
Enterprise ESG platforms are built for this. 4Seer Technologies pairs 4Scope, its GRI-certified reporting product, with 4Vue for the data pipelines that keep asset-level information flowing into one place.
Tenant Engagement as a Data Function
For commercial landlords, tenant emissions sit inside Scope 3 category 13. GRESB scores you on how well you engage tenants, and ASRS asks for Scope 3 disclosure where the data is reliable. The problem is usually access, not willingness.
What tends to work across Australian office and retail portfolios:
- Green lease clauses that require tenants to share utility data and allow sub-metering at fit-out
- Tenant scorecards tracking fit-out sustainability, energy use and waste separation
- Shared-value offers such as bulk power purchase agreements, co-funded retrofits and pooled renewable procurement
Green lease terms are now common in premium Sydney, Melbourne and Brisbane office deals. The data-sharing clauses inside them are what turn tenant Scope 3 emissions from a rough estimate into a real number.
Embodied Carbon Disclosure Is Arriving Faster Than Expected
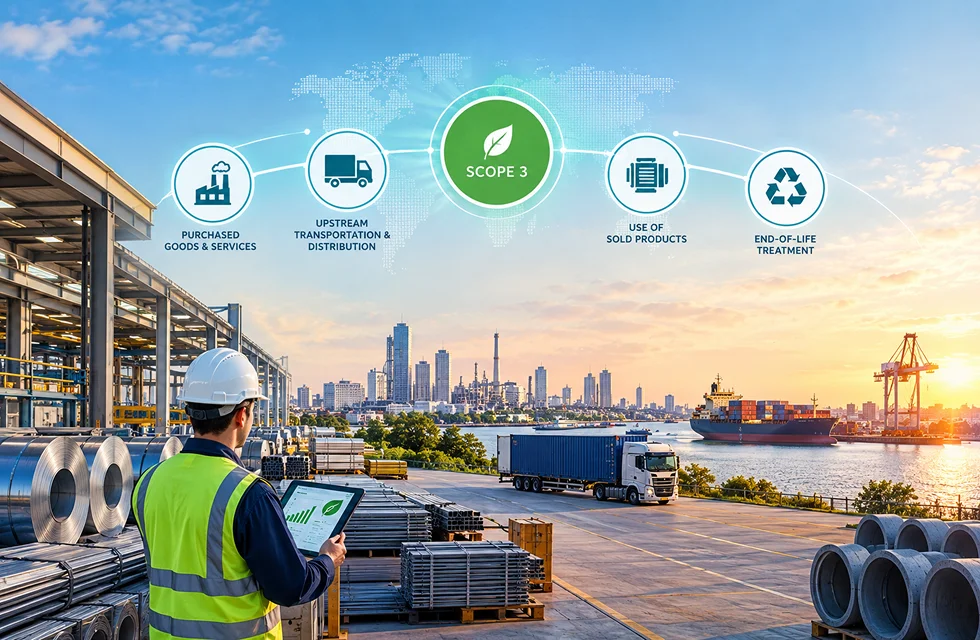
Embodied carbon is no longer a niche issue. GRESB now scores it, and ASRS S2 asks for it under Scope 3 categories 1 and 2, which cover purchased goods and capital goods, if you have significant development or major refurbishment activity.
What real estate teams should have in place before 2027:
- Environmental Product Declarations (EPDs) for the major materials going into current development projects
- Life cycle assessment built into design work, not added on at the end
- Supplier data collection that survives procurement handovers and tier-two subcontracting
- Baseline and target intensity numbers in kgCO2e per square metre, benchmarked to Green Building Council of Australia guidance
NABERS does not yet rate embodied carbon, though a NABERS Embodied Carbon tool has been in development. Institutional investor questionnaires now routinely ask for upfront carbon numbers during due diligence.
Building an Aligned Reporting Architecture
An aligned setup usually has one operational data layer feeding a calculation engine. That engine generates NABERS submissions, GRESB responses and ASRS disclosures from the same numbers, with a full audit trail. Governance sits alongside the pipeline. One materiality register. One defined Scope 3 boundary. Internal audit trails that carry through to the auditor signing off on ASRS.
Most portfolios do not get there in one step. The usual path is to consolidate NABERS and GRESB feeds first, then extend the same setup to cover ASRS scope categories as the assurance deadline gets closer.
4Seer Technologies has worked on ESG compliance across 10 countries and delivered against major frameworks including GRI, CDP, TCFD, CSRD, ESRS and BRSR. The firm’s real estate work combines GRI-certified reporting through 4Scope with the data engineering that keeps three frameworks consistent on one dataset. Explore the 4Seer ESG platform for portfolio-scale disclosure.
Ready to Align Your ESG Reporting Architecture?
Bring your NABERS, GRESB and ASRS reporting onto one data platform built for portfolio-scale disclosure. Talk to the 4Seer Technologies team about a readiness assessment for your Australian real estate portfolio, or take a closer look at the 4Seer ESG solutions for GRI-certified reporting.
Frequently Asked Questions
Is ASRS Mandatory for Australian Real Estate Portfolios in 2026?
ASRS goes by entity size, not by sector. If your portfolio owner is a Group 1 entity with over $500M in revenue, $1B in assets or 500-plus staff, you are already reporting. Group 2 entities begin from financial years starting 1 July 2026. Most listed A-REITs and large unlisted wholesale funds fall into Group 1 and are now producing AASB S1 and S2 reports alongside their usual NABERS and GRESB submissions.
Can NABERS Data Satisfy ASRS Emissions Disclosure Requirements?
NABERS Energy gives you solid Scope 1 and 2 emissions numbers at asset level, which cover a large part of what ASRS S2 asks for on operational emissions. It does not cover Scope 3, tenant emissions outside base building use, or embodied carbon. Most Australian portfolios treat NABERS as their operational emissions base and add other data streams to fill in the rest of the ASRS picture.
How Does GRESB Participation Help With ASRS Reporting?
GRESB and ASRS overlap on governance, climate risk analysis and performance disclosure. Portfolios that already score well on GRESB usually have a lot of the S2 groundwork done, especially on board oversight documents and physical risk analysis. Reusing GRESB submission data to pre-fill ASRS disclosures cuts reporting effort and keeps your investor-facing and regulatory numbers consistent with each other.
What Is the Best Software for Aligning NABERS, GRESB and ASRS Reporting?
Look for platforms that plug directly into utility data, building management systems and tenant sub-meters, and then map that data across multiple frameworks. 4Seer Technologies offers 4Scope, a GRI-certified reporting product delivered against six major sustainability frameworks (GRI, CDP, TCFD, CSRD, ESRS, BRSR), paired with 4Vue for enterprise data pipelines. That combination fits Australian real estate portfolios juggling several reports at once.
When Should Real Estate Portfolios Start Disclosing Embodied Carbon?
If you have active development or major refurbishment work, start collecting EPD and life cycle assessment data now. GRESB already scores embodied carbon, and ASRS S2 asks for it under Scope 3 categories 1 and 2 where the impact is material. Waiting for NABERS embodied carbon ratings to be finalised may put you behind investor expectations, since Australian institutional capital is already moving toward upfront carbon transparency.