A Tier-2 steel supplier in South Korea receives an email from an Australian equipment manufacturer’s procurement team. The buyer wants emissions data broken down by product and by tonne shipped, for the last financial year. The reply comes back as a single company-wide Scope 1 and 2 number, plus a link to a global sustainability report. Neither can be tied to the actual products the Australian buyer received, and neither will pass an assurance check. This kind of exchange has become the single biggest data-quality problem in Scope 3 Category 1 reporting across Australian manufacturing.
The Australian Sustainability Reporting Standards came into effect for the largest entities on 1 January 2025, and the rules will reach mid-sized and smaller entities through 2027. Under these standards, Scope 3 is no longer a stretch goal. It is a reported number that must be measured, backed up with evidence, and defended in front of an auditor, and the pressure also flows down the chain to the smaller manufacturers supplying disclosing companies.
The Scope 3 Categories That Matter Most for Australian Manufacturers
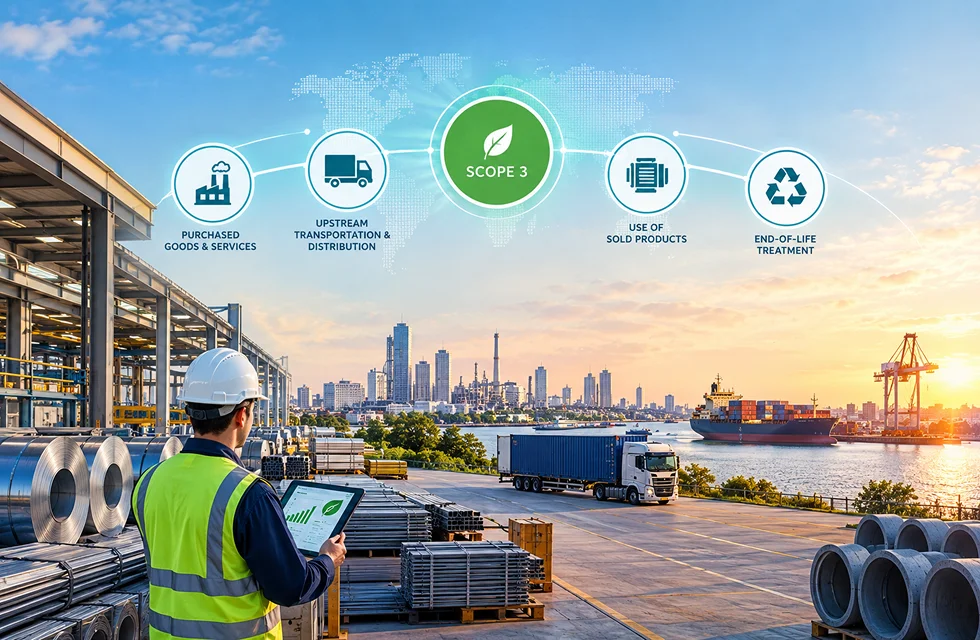
The Greenhouse Gas Protocol lists 15 Scope 3 categories, but for most Australian manufacturers only four carry real weight in the numbers.
Category 1 (Purchased Goods and Services) is usually the biggest single item, because raw materials like steel, aluminium, cement, chemicals, plastics, and electronic parts carry a lot of embedded carbon, especially when they come from countries with coal-heavy power grids.
Category 11 (Use of Sold Products) is the largest item for anyone making equipment that uses energy in the field, such as pumps, motors, HVAC systems, and industrial vehicles. Once a product runs for 15 years on a customer’s site, its total electricity draw adds up to more than any factory improvement can cancel out.
Category 4 (Upstream Transportation and Distribution) matters wherever long-distance freight inside Australia combines with international shipping from suppliers, and procurement teams can shape it directly by changing transport mode or combining loads.
Category 12 (End-of-Life Treatment) ties product design choices to how much of the product ends up in landfill, how much can be recycled, and the requirements set by the Product Stewardship Act.
The remaining categories (capital goods, fuel and energy activities, waste, business travel, employee commuting) still have to be reported, but rarely move the total by a large amount. CDP’s Global Supply Chain research has shown that suppliers reporting through the platform often carry Scope 3 emissions many times larger than their direct emissions, which is a useful reminder of where the biggest reductions can come from.
Why Supplier Engagement Fails and What Works Instead
Most supplier engagement programs run into the same three problems: the request goes to the wrong person, the template asks for numbers the supplier does not track, and there is no real cost to a supplier who ignores it. Fixing this is more about the process than the wording.
The first practical step is to send the request through the procurement contract owner rather than a general sustainability inbox. Contract owners can influence renewal terms and order volumes, which a policy team cannot. Suppliers should then be sorted by how much you spend with them and how carbon-heavy their inputs are, so that the top group gets a scheduled phone call while the smaller ones receive a simpler online form.
Each supplier should also be given a choice between sharing their own measured emissions or letting you apply a spend-based estimate on their behalf, since smaller suppliers usually cannot produce measured figures and should not be penalised for saying so.
The request should also be tied into normal commercial reviews, so that a supplier who skips two reporting cycles has a procurement conversation about future orders. As DCCEEW’s climate-related financial disclosure guidance explains, Scope 3 reporting is only as credible as the engagement process behind it, not the design of the survey form.
Designing a Data Collection Template Suppliers Will Complete
A good template is short, uses consistent units, and comes pre-filled wherever possible. What you leave out matters as much as what you include.
The template should ask for the reporting period (financial year, calendar year, or rolling 12 months), the product or service supplied and how it maps to your purchase order lines, the quantity supplied in physical units like tonnes, litres, or kWh rather than only in dollars, the Scope 1 and Scope 2 emissions linked to that volume where the supplier can calculate them, the method used to work out those numbers, and any third-party verification statement the supplier holds.
At the same time, drop any question that asks the supplier to interpret your reporting boundary, any open-text field longer than one line, and any request for methodology documents beyond a single-line reference. Pre-fill the supplier’s name, the products they ship to you, and the reporting period. Send the template as an editable spreadsheet with the structure locked, not as a portal login, because suppliers tend to finish spreadsheets in their own time and rarely return to portals.
For suppliers who cannot share their own measured emissions, use spend-based factors from the Australian Government’s National Greenhouse Accounts Factors publication as the default. Record the choice in your inventory register with a date to review it, so that the assumption is clear to auditors later.
Verification: Getting Ready Before Your Auditor Arrives
Under AASB S2, Scope 3 emissions need limited assurance from the second year of reporting for entities in scope, and reasonable assurance will follow on a schedule set by the Auditing and Assurance Standards Board. This is a year-round job, not a year-end scramble.
Every emissions number in the inventory should link back to a source document (an invoice, a meter reading, a supplier email) that a reviewer can open in a couple of clicks. Emission factors should also be version-controlled, with the date, source, and reason for any mid-year change written down.
Reconciling the Scope 3 inventory to the financial ledger every quarter is a useful safety check, because Category 1 emissions should track purchase order value inside a set tolerance, and a big gap usually points to either missing data or the wrong factor. Exclusions are worth writing down clearly.
If you leave out Category 15 (Investments) because the entity does not hold any equity stakes, say so. A stated exclusion reads as a considered decision to a reviewer, while a silent gap reads as an oversight.
Manufacturers who run these checks every quarter usually go into assurance with fewer items to fix than those who wait until year-end.
Where 4Seer Fits In
4Seer Technologies works with manufacturers across 10 countries to put value chain reporting into day-to-day operation. Our GRI-certified 4Scope platform sorts supplier data into GHG Protocol categories and produces reports aligned to GRI, CDP, TCFD, CSRD, ESRS, and BRSR from a single dataset. With over 30 enterprise data source integrations, procurement systems, ERP feeds, and supplier portals come together without manual matching, which shortens the path from raw Category 1 data to a report an auditor can review.
To see how a Scope 3 program would be scoped for your operation, visit our ESG and sustainability solutions page or ask for a scoping conversation with our value chain team.
Frequently Asked Questions
Do Australian Manufacturers Legally Have to Report Scope 3 Emissions in 2026?
Yes, if your entity meets the Group 1 or Group 2 thresholds under the Australian Sustainability Reporting Standards. Group 1 entities began mandatory climate reporting on 1 January 2025, with Scope 3 required from the second reporting year. Group 2 obligations begin on 1 July 2026. Voluntary Scope 3 reporting still matters for smaller manufacturers chasing contracts with listed customers, who often pass disclosure requirements up the supply chain.
Which Scope 3 Category Should Australian Manufacturers Tackle First?
Category 1 (Purchased Goods and Services) is the right starting point for most manufacturers, because it is usually the largest part of the footprint and gives procurement the clearest lever to reduce it. Manufacturers who sell equipment that uses energy should also focus on Category 11 (Use of Sold Products), since a product designed today will keep producing emissions on customer sites for the next decade or more.
How Much Does a Scope 3 Inventory Cost to Build for an Australian Manufacturer?
In our experience, a full Scope 3 inventory for a mid-sized Australian manufacturer usually costs between AUD 80,000 and AUD 250,000 in the first year, depending on how many suppliers are in scope and how mature the existing data is. Ongoing annual costs fall clearly once templates, ERP integrations, and supplier routines are in place. Platform-led delivery generally costs less than a pure consulting approach that rebuilds the inventory each year.
Can Spend-Based Emission Factors Meet AASB S2 Assurance Requirements?
Spend-based factors are acceptable under AASB S2 for limited assurance, as long as the method, factor source, and how they were applied are written down clearly in the basis of preparation. Auditors also expect a plan to move the largest suppliers to measured or supplier-specific data over time. Sticking with spend factors for material suppliers is likely to draw a qualification once reasonable assurance kicks in.
What Is the Fastest Way to Improve Supplier Response Rates on Emissions Data?
Send the request through the procurement contract owner rather than a sustainability inbox, sort suppliers by spend, and phone the top group individually. Tie response performance to renewal reviews so that missed submissions come up during commercial conversations. Manufacturers who use these three levers together usually see response rates climb noticeably over two reporting cycles without needing extra headcount in the sustainability team.